Hospitality crowdfunding: A Reg CF readiness guide
Hospitality crowdfunding can let an eligible company seek investment through Regulation Crowdfunding, or Reg CF. However, a hotel, restaurant, venue, or mixed-use project must first identify the legal issuer and the rights it controls. The team also needs a supported budget, reliable operating records, and a realistic plan for required disclosures. Therefore, the hospitality label alone does not establish eligibility or fit.
Key takeaways
- First, name the exact company that would offer securities and receive the proceeds.
- Next, document how that issuer relates to the property owner, operator, manager, brand, food-service business, and other affiliates.
- Also, connect each use of proceeds to current leases, contracts, quotes, permits, schedules, and operating records.
- In addition, treat guest, customer, membership, and local-community reach as audience evidence, not as investor demand.
- Finally, plan for investor records, annual reporting, governance, and communications after the offering closes.
What does hospitality crowdfunding mean?
Hospitality crowdfunding is a broad phrase. It can refer to donations, rewards, loans, or securities. This guide focuses on a possible securities offering under Reg CF.
Under current SEC rules, eligible companies may offer and sell securities through one online SEC-registered intermediary. The aggregate Reg CF offering limit is $5 million in a 12-month period. In addition, the issuer files Form C and provides required information to investors and the intermediary.
Reg CF is not a hospitality-specific exemption. As a result, a project does not receive different securities treatment because it involves lodging, food, events, tourism, or a community destination. The actual issuer, security, records, risks, and offering facts control the analysis.
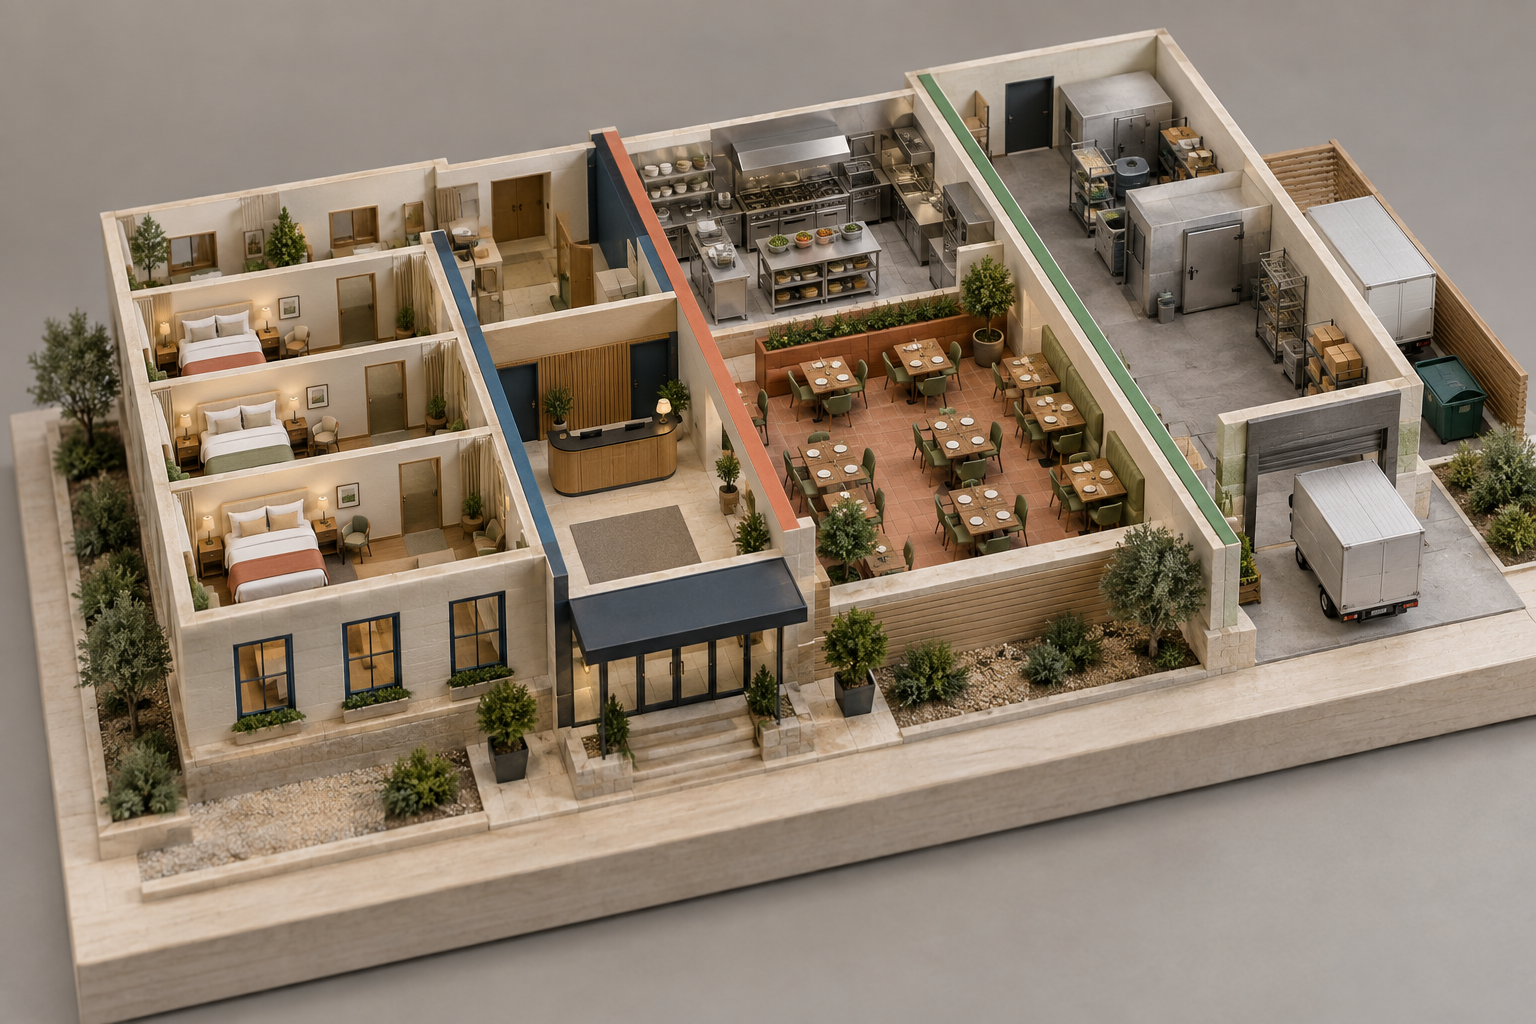
A hospitality capital plan may involve several kinds of businesses. For example, one company might own a building while another operates the hotel. A management company may employ staff, and a separate entity may run the restaurant. Meanwhile, a franchisor, landlord, lender, or local authority may control important rights.
Start hospitality crowdfunding with the legal issuer
First, identify the company that would sell the securities. Then, confirm what that company owns, leases, licenses, manages, owes, and may lawfully do.
Invown publishes its issuer onboarding steps, which list the entity documents this stage calls for — from formation records to the EDGAR filer id.
The trade name on the building may not be the issuer. Likewise, the property owner may not receive room or restaurant revenue. A management company may control operations without owning the real estate. Therefore, the offering story should not blend separate companies into one business unless the legal and economic facts support that description.
Form C calls for information about the issuer’s business, ownership, officers, directors, capital structure, indebtedness, financial condition, related-party transactions, intended use of proceeds, and material risks. Consequently, the issuer’s records should support the public explanation.
If the operating company is the issuer
The analysis should center on the entity that earns operating revenue and pays operating expenses. Its records may include guest or customer revenue, payroll, vendor agreements, licenses, insurance, reservations, and management obligations.
However, the operating company should not imply that it owns real estate, equipment, intellectual property, or permits held by someone else. Instead, explain the contracts that give the issuer access to those resources. Also, disclose material limits, renewal terms, termination rights, and dependencies when required.
If the property owner or sponsor entity is the issuer
The analysis may focus on acquisition, renovation, repositioning, or property-level operations. In that case, clarify how the issuer connects to the operator, manager, brand, tenants, lenders, and contractors.
In addition, distinguish property economics from operating-business economics. A building appraisal, construction budget, management forecast, or brand study serves a specific purpose. None of those items alone establishes future occupancy, revenue, value, investor demand, or an offering result.
If several affiliates are involved
Pause for legal and accounting review. The team should map which entity owns each asset, signs each contract, employs each person, receives each revenue stream, and bears each obligation.
Related-party agreements, fees, loans, transfers, guarantees, and shared services may be material. Accordingly, the structure should make the movement of proceeds and the basis for the offered security understandable. It should not hide economic dependence behind a familiar property or brand name.
Connect the use of proceeds to a hospitality plan
Reg CF requires a reasonably detailed description of the intended use of proceeds. Therefore, “open a hotel” or “expand the restaurant” is not enough for a working budget.
Depending on the issuer, a hospitality budget may include:
- property acquisition or lease deposits;
- design, permitting, renovation, or tenant improvements;
- guest-room, kitchen, point-of-sale, or building equipment;
- furniture, fixtures, smallwares, and opening inventory;
- licenses, insurance, utilities, and technology setup;
- brand, management, reservation, or franchise obligations;
- pre-opening hiring and training for the issuer’s own team;
- working capital tied to a documented operating plan; or
- intermediary, legal, accounting, escrow, communications, and post-close work.
Next, connect each material item to a current source. For example, a renovation line should tie to plans, bids, and a contingency method. Equipment should tie to quotes and installation requirements. A management or brand payment should tie to the governing agreement.
Also, explain how the target and maximum offering amounts affect the plan. A lower closing may support fewer workstreams, a smaller scope, or a different sequence. Yet neither amount should be presented as assuring an opening date, completion, occupancy, operating performance, or fundraising outcome.
When you build that budget, platform costs belong in it too: Invown publishes its full plan pricing, and the Invown savings calculator shows the all-in cost at different raise sizes and timelines.
Use a six-part hospitality crowdfunding readiness screen
This screen helps a team organize questions before intermediary review. It does not determine eligibility, acceptance, or offering terms.
1. Is the issuer identity clear?
Can the team name one legal company and produce its formation, ownership, governance, tax, banking, debt, and capitalization records? If not, start with the entity map.
2. Does the issuer control the project rights?
Confirm who owns or leases the property. Then, identify who holds the licenses, management agreement, brand rights, equipment, reservation contracts, and other operating permissions.
If the issuer depends on another company, document that relationship. Also, identify material consent, renewal, termination, transfer, or change-of-control limits for counsel and intermediary review.
3. Do the financial records match the business?
Form C requires financial statements at the level applicable to the offering amount and the issuer’s circumstances. Therefore, reconcile the issuer’s books, bank activity, taxes, debt, capitalization, and related-party transactions early.
Hospitality records may need additional separation. For instance, room revenue, food and beverage revenue, management fees, owner expenses, deposits, gift-card liabilities, and capital spending should not be mixed without a supported accounting basis.
4. Is the budget grounded in current evidence?
Review leases, title or purchase records, construction plans, permits, contractor bids, equipment quotes, management terms, licenses, insurance, and opening dependencies. Then, mark each item as current, stale, missing, or under review.
Also, test the schedule against approvals and contractual milestones. The public draft should describe uncertainty fairly rather than convert a working schedule into a promised date.
5. Is the audience reachable and appropriate?
A hospitality business may know guests, diners, members, neighbors, vendors, event customers, and local partners. Still, those relationships do not establish investment interest, eligibility, or capacity.
Therefore, document the source, permission, owner, and approved use of each audience record. Keep ordinary customer communications, testing-the-waters indications, live-offering notices, and investment commitments in separate workflows.
6. Can the issuer support investors after closing?
An offering can add ongoing work. The issuer may need cap-table or transfer-agent records, investor communications, tax coordination, governance, and annual Reg CF reporting.
Accordingly, assign owners before launch. A property manager, brand, landlord, portal, or marketing provider does not automatically assume the issuer’s post-close obligations.
Which hospitality risks need a clear explanation?
Hospitality projects vary widely. Nevertheless, the disclosure process should address the material risks that apply to the actual issuer and plan.
Those risks may involve:
- site control, lease renewal, title, zoning, or property condition;
- construction scope, cost changes, permits, inspections, or contractor performance;
- liquor, food-service, lodging, event, health, or other licenses;
- brand, franchise, reservation, or management-company dependencies;
- opening delays, seasonality, demand changes, or revenue concentration;
- staffing, wage, training, vendor, utility, and insurance pressures;
- existing debt, lender consent, liens, guarantees, or refinancing needs;
- related-party arrangements and fees; or
- the issuer’s ability to maintain records and required reports after closing.
The list is not a substitute for issuer-specific review. Instead, use it to find assumptions that need documents, qualifications, or clearer ownership.
For that reason, a hospitality crowdfunding draft should treat risks as issuer-specific facts rather than generic boilerplate.
In addition, avoid unsupported claims about market demand, future occupancy, guest spending, property value, returns, opening dates, or likely fundraising. Historical operating data also needs a clear period, source, scope, and explanation of material limitations.
When may hospitality crowdfunding be a poor fit?
The fit is weak when the issuer, property rights, proceeds, or operating plan remains unclear. It may also be weak when the company cannot produce reliable records or support material statements.
Pause the process if:
- the property owner, operating company, manager, and proposed issuer have not been separated;
- the issuer lacks documented rights to the property, brand, equipment, permits, or revenue described;
- the budget relies on stale bids, unresolved site control, or unsupported opening assumptions;
- the books mix several entities or businesses without a defensible accounting basis;
- a material contract requires consent that has not been evaluated;
- the campaign would rely on unverified occupancy, revenue, valuation, demand, or return claims;
- the audience plan treats guests, followers, or community interest as likely investors; or
- the team cannot support investor records and required reporting after closing.
Instead, the project may need to resolve its structure, records, contracts, site plan, or financing mix first. Counsel, accountants, and qualified advisers can assess the facts without assuming Reg CF is the answer.
Hospitality crowdfunding preparation checklist
Before an intermediary review, organize:
- the exact issuer name, formation records, ownership, and governance documents;
- a plain-English map of property, operating, management, brand, food-service, and affiliate roles;
- property ownership, lease, franchise, management, reservation, and material vendor agreements;
- permits, licenses, insurance, plans, bids, equipment quotes, and schedule dependencies;
- a source-controlled budget for the target and maximum offering amounts;
- financial statements and supporting books for the proposed issuer;
- debt, capitalization, related-party, prior-offering, and guarantee records;
- material risks tied to the site, project, operator, contracts, construction, and operating plan;
- evidence and permission for every audience, property, brand, market, and performance statement;
- an approved communications process for pre-filing and live-offering periods; and
- a post-close plan for investor records, governance, tax work, and Reg CF reporting.
Finally, assign an owner and review date to each item. A visible gap is more useful than a polished narrative that the records cannot support.
A practical next step
Hospitality crowdfunding starts with a legal issuer and a documented capital plan. First, separate the property, operator, manager, brand, and affiliates. Then, connect the budget, contracts, financial statements, project schedule, audience evidence, and material risks to that issuer.
Much of this preparation maps to materials Invown already publishes: the onboarding steps, plan pricing, and the issuer articles in the help center. Book a consultation to walk your project against the six-part screen. A consultation does not establish eligibility, acceptance, or any fundraising outcome.
Invown Corp owns and maintains the general technology platform. Reg CF funding-portal activity identified on the site is conducted through Invown Funding Portal LLC, an SEC-registered funding portal and FINRA member. This article does not provide legal, tax, accounting, financial, real-estate, franchise, or investment advice.