Reg CF annual reporting: A post-close issuer checklist
Reg CF annual reporting starts with a deadline tied to the issuer’s fiscal year, not the offering’s closing date. After an issuer sells securities under Regulation Crowdfunding, the work can include a Form C-AR filing, financial statements, a website post, and supporting records. Therefore, founders should assign this workflow before the first post-close fiscal-year deadline approaches.
Key takeaways
- First, calculate the Form C-AR deadline from the end of the fiscal year covered by the report.
- Next, map every required disclosure to a current record and a responsible reviewer.
- In addition, prepare the applicable financial statements and certification path under the current rules.
- Finally, file on EDGAR, post the annual report on the issuer’s website, and retain proof of both steps.
- Do not stop reporting based on an assumption. Instead, confirm a Rule 202 termination condition and file Form C-TR when required.
What triggers Reg CF annual reporting?
Rule 202 applies when an issuer has offered and sold securities under Regulation Crowdfunding. Consequently, an initial or rolling closing can create reporting work even while other offering activity continues.
The SEC’s current interpretation addresses that situation. If an offering remains open more than 120 days after the issuer’s fiscal year end, several filings may overlap. Specifically, the issuer may need a Form C-AR, a Form C/A with updated financial statements, and applicable progress updates. Counsel and the intermediary should evaluate the issuer’s actual timeline and facts.
Meanwhile, the annual-report deadline runs from the fiscal year covered by the report. Rule 203 requires filing no later than 120 days after that fiscal year ends. It does not provide 120 days from the offering’s final closing.
For example, a calendar-year issuer usually counts from December 31. However, the team should confirm the actual fiscal year, any co-issuer, and the current filing calendar. A generic date calculator cannot resolve every filing question.
What does Form C-AR cover?
A Form C-AR is not merely a short investor update. Instead, Rule 202 requires specified issuer information, financial statements, and a description of financial condition.
Under the current Form C instructions, the annual report covers several categories of information. These include:
- the issuer’s identity, legal status, address, and website;
- directors, officers, and their relevant business experience;
- beneficial owners of 20% or more of voting equity, calculated under the applicable rule;
- the business, anticipated business plan, employee count, and material risk factors;
- selected offering information and the issuer’s ownership and capital structure;
- material indebtedness, financial condition, and financial statements;
- specified related-party transactions; and
- certain exempt offerings conducted during the applicable lookback period.
Accordingly, the team should use the current rule and Form C instructions as the source list. A prior offering statement can help with orientation, but it may contain stale people, ownership, debt, risks, or business information.
How do the financial statements work?
The SEC’s issuer guide states that an audit or review is not automatically required for the annual report. However, Rule 202 adds an important qualification. If reviewed or audited financial statements from an independent public accountant are available, the issuer must provide them.
Otherwise, the issuer provides the required financial statements with the principal executive officer’s certification. The certification states that the statements are true and complete in all material respects. Therefore, the accounting close, U.S. GAAP preparation, source support, and certification process need clear owners.
In addition, the filing includes selected financial data for the two prior fiscal years. The current Form C instructions identify items such as assets, cash, receivables, debt, revenue, cost of goods sold, taxes paid, and net income. As a result, the numbers in the filing, attached statements, books, and explanatory text should reconcile.
Build a Reg CF annual reporting workflow
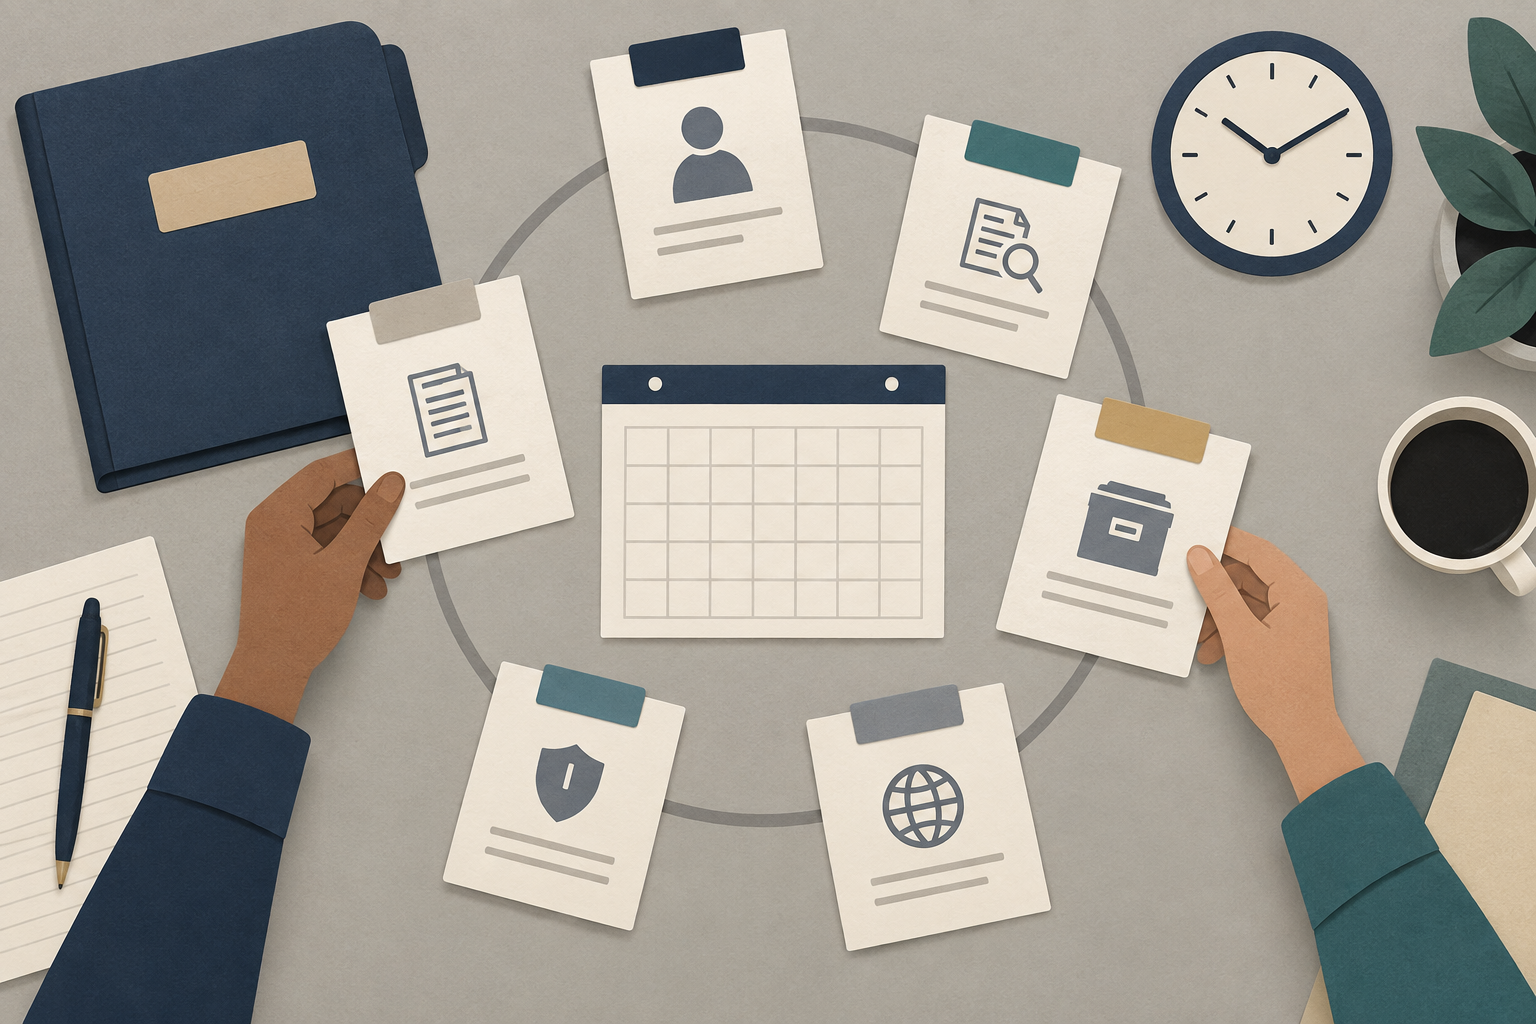
A useful workflow begins before drafting prose. First, create a calendar from the fiscal year end and work backward from the 120-day deadline. Then, add internal due dates for bookkeeping, financial statements, disclosure updates, legal review, signatures, EDGAR filing, and website posting.
Next, build a source map. Each disclosure should connect to a current document, a named owner, a reviewer, and a last-confirmed date. For example, ownership should tie to the cap table and governing records. Debt should tie to signed instruments and current balances.
1. Confirm the issuer and reporting perimeter
First, identify the legal issuer and any co-issuer. Then, confirm the fiscal year end, prior Reg CF sales, earlier Form C filings, and reporting history. In addition, preserve the EDGAR accession numbers and filed exhibits.
2. Refresh people, ownership, and entity records
Next, update directors, officers, business experience, and covered ownership information. Reconcile the cap table with issuances, transfers, conversions, repurchases, and governing approvals. Therefore, do not rely only on an investor spreadsheet or the original campaign page.
3. Reconcile the business and financial record
Meanwhile, close the books and document material changes to the business. Review debt, related-party transactions, capitalization, risks, operations, and the financial-condition discussion. If a number or statement changed, keep support for the new version and the reason for the change.
4. Draft from the current requirements
Then, use the current Form C instructions and Rules 202 and 203. Assign each required item to a source and reviewer. Moreover, distinguish a required disclosure from a voluntary investor communication or marketing update.
5. Review the complete filing package
Afterward, have securities counsel and the accounting team review the package within their respective roles. Check names, dates, ownership, totals, cross-references, attachments, website language, and signatures. Finally, confirm that the filing is accurate and not misleading in context.
6. File, post, and retain evidence
Once approved for filing, submit the Form C-AR on EDGAR. Also post the annual report on the issuer’s website as Rule 202 requires. Then, retain the accepted filing, accession number, posted file, live URL, posting date, approvals, and source package.
The filing and website copy should match. Consequently, a team should not treat the website post as an optional marketing task.
What if the annual report needs a material correction?
Rule 203 requires an amendment when a material change to a filed annual report becomes necessary. The issuer files that amendment on Form C-AR/A as soon as practicable after discovering the need.
Therefore, a post-filing review process matters. Route questions about possible errors or omissions promptly to securities counsel. In addition, keep the original filing, the amended filing, and the decision record together.
This amendment process differs from correcting a typo on an ordinary webpage. Accordingly, the issuer should not quietly replace a posted report and assume the regulatory record is complete.
When may Reg CF annual reporting end?
Reporting does not end merely because the raise closed, a year passed, or investor activity became quiet. Instead, Rule 202 lists five termination conditions. The obligation continues until one of these occurs:
- the issuer becomes subject to Exchange Act reporting under Section 13(a) or 15(d);
- the issuer filed at least one required annual report after its most recent Reg CF sale and has fewer than 300 holders of record;
- the issuer filed the required annual reports for at least the three most recent years after its most recent Reg CF sale and has no more than $10 million in total assets;
- the issuer or another party repurchased all securities issued under Regulation Crowdfunding, including full payment of debt securities or complete redemption of redeemable securities; or
- the issuer liquidated or dissolved under state law.
Even when a condition appears to apply, the analysis should use current holder, asset, security, and filing records. Moreover, Rule 203 requires an eligible issuer to file Form C-TR within five business days after it becomes eligible to terminate reporting. The notice advises investors that the issuer will stop reporting under Regulation Crowdfunding.
Therefore, do not mark the obligation complete until counsel confirms the condition and the Form C-TR process. A cap-table count or repayment event alone is not the filing.
Common annual-reporting mistakes to prevent
Several process gaps can create avoidable risk:
- calculating from the closing date instead of the fiscal year end;
- assuming the original Form C remains current;
- omitting the issuer-website posting step;
- using cap-table data that does not reflect later issuances, transfers, or repurchases;
- overlooking available reviewed or audited financial statements;
- allowing financial statements, selected data, and narrative disclosures to conflict;
- treating investor updates as a substitute for Form C-AR;
- failing to evaluate a material correction for Form C-AR/A; or
- stopping reports without confirming a termination condition and filing Form C-TR.
In addition, missed annual reports can affect more than investor communications. The Form C eligibility certification asks about required ongoing reports during the preceding two years. Therefore, issuers considering another Reg CF offering should address reporting history early with counsel and the intended intermediary.
Reg CF annual reporting checklist
Use this checklist to organize a review. It is not a substitute for the current rules or professional advice.
- Confirm the legal issuer, any co-issuer, and the fiscal year end.
- List every prior Reg CF closing and relevant Form C filing.
- Calculate the 120-day deadline and internal review dates.
- Assign an owner and reviewer to every required disclosure.
- Reconcile entity, officer, director, ownership, and capitalization records.
- Reconcile debt, related-party transactions, prior exempt offerings, and material risks.
- Prepare the applicable U.S. GAAP financial statements and certification path.
- Reconcile selected financial data with the statements and books.
- Review the full filing, exhibits, signatures, and website copy.
- File Form C-AR on EDGAR and retain the acceptance record.
- Post the annual report on the issuer’s website and retain proof.
- Escalate possible material corrections for Form C-AR/A analysis.
- Reassess termination eligibility and file Form C-TR when required.
Finally, keep the reporting file usable by the people who will handle the next cycle. A repeatable record is more reliable than reconstructing the process each year.
A practical next step
Reg CF annual reporting belongs in the raise plan before securities are sold. The deadline, records, reviewers, filing process, and website post all need assigned owners. In addition, future offerings and investor service may depend on an accurate reporting history.
If you are planning a raise and want to discuss the workflow around it, book a meeting with Invown. The discussion can identify process questions, but it does not establish eligibility, acceptance, compliance, timing, investor interest, or an offering outcome.
Invown Corp owns and maintains the site as a technology company. Reg CF funding-portal activity identified on the site is conducted through Invown Funding Portal LLC, an SEC-registered funding portal and FINRA member. Invown does not provide legal, tax, accounting, financial, or investment advice.
Sources and editorial review notes
Primary and first-party sources reviewed September 24, 2026:
- 17 CFR 227.202, ongoing reporting requirements, including report content, financial-statement treatment, the 120-day deadline, and termination conditions.
- 17 CFR 227.203, filing requirements and form, including Form C-AR, Form C-AR/A, and Form C-TR requirements.
- SEC Regulation Crowdfunding guidance for issuers, including annual-report timing, website posting, and the general reporting framework.
- SEC Form C and current instructions, including annual-report disclosure categories, XML financial data, certification, and signature instructions.
- SEC Regulation Crowdfunding interpretations, last updated July 9, 2026, including current guidance for an offering that remains ongoing after the annual-report deadline.
- FINRA Funding Portal Rule 200(c), applied conservatively to the complete public-facing package.
- Invown post-close investment management page and Invown issuer process, checked for current entity wording, service boundaries, and issuer context.
This article is educational information, not legal, tax, accounting, financial, or investment advice. Issuers should use the current rules, their own records, and qualified advisers for the actual filing.