Reg CF advertising rules: An issuer checklist
Reg CF advertising rules change with the timing, channel, content,
and speaker involved. A message away from the intermediary’s platform
may face a different limit than a discussion inside the platform’s
communication channel. Therefore, an issuer should classify each
communication before drafting it and route the final version through the
required review process.
Key takeaways
- First, identify whether the message comes before or after the issuer
files Form C. - Next, identify the channel and decide whether the message includes
any terms of the offering. - In addition, direct off-platform notices to the intermediary’s
platform and keep them within Rule 204’s permitted information. - Also, review promoter compensation and disclosure duties before
anyone speaks for the issuer. - Finally, keep communications accurate, balanced, current, and
consistent with the filed disclosures.
How do Reg
CF advertising rules split the channels?
The rules do not treat every issuer message as interchangeable.
Instead, the analysis begins with timing and channel.
Before a Form C filing, an issuer may use Regulation Crowdfunding
Rule 206 to test the waters if it satisfies the rule’s conditions. Those
communications are offers for federal antifraud purposes. They also
require specific statements about money, acceptance, and the nonbinding
nature of an indication of interest.
After filing, Rule 204 governs advertising that includes terms of the
offering. Away from the intermediary’s platform, that communication must
fit within the rule’s notice format. However, an issuer may discuss
offering terms through communication channels on the intermediary’s
platform.
The SEC also distinguishes communications that do not include
offering terms. Its current interpretations say Rule 204’s notice limit
does not apply merely because an advertisement exists. Nevertheless,
other securities-law, antifraud, privacy, advertising, and platform
requirements may still apply.
Consequently, a team should not reduce the analysis to “advertising
is allowed” or “advertising is prohibited.” The useful question is more
specific: what will this message say, where will it appear, when will it
appear, and who prepared or paid for it?
What may a Rule 204 notice
include?
Reg CF advertising rules limit what an off-platform notice may
contain when it advertises offering terms. Specifically, Rule 204(b)
provides three categories of information.
An off-platform notice that advertises offering terms may include
three categories of information under Rule 204(b).
First, it may state that the issuer is conducting an offering under
Section 4(a)(6). It may also name the intermediary and direct the reader
to that intermediary’s platform. A written notice can include a
link.
Second, the notice may include the terms of the offering. The rule’s
instruction defines those terms to include:
- the amount of securities offered;
- the nature of the securities;
- the price of the securities;
- the closing date of the offering period;
- the planned use of proceeds; and
- the issuer’s progress toward its funding target.
Third, the notice may include limited factual information about the
issuer’s legal identity and business location. Rule 204 lists the
issuer’s name, address, phone number, website, representative email
address, and a brief business description.
Therefore, a Rule 204 notice is not a condensed pitch deck. A team
should avoid adding unsupported praise, forecasts, testimonials,
investment conclusions, urgency, or omitted qualifications. Moreover,
the linked platform page should contain the current filed information
needed for a prospective investor’s review.
What belongs on the
intermediary’s platform?
The intermediary’s communication channel provides room for discussion
about the offering’s terms. Even there, however, identity and
affiliation matter. The issuer must identify itself, and a person acting
for the issuer must identify that affiliation.
In addition, the conversation must remain accurate in context. A
short reply can mislead if it omits a qualification, conflicts with Form
C, or presents an opinion as a verified fact. Consequently, the team
should route substantive answers through a source and review
process.
For example, a founder may answer a question about the stated use of
proceeds. The answer should match the current filing and any material
amendment. However, the founder should not turn that answer into a
prediction about revenue, valuation, investor returns, demand, or the
offering’s outcome.
The Invown
offering-page guide explains how organized disclosures support
investor review. In addition, the Invown issuer process
page describes the broader platform workflow. Neither page replaces
advice about a specific communication.
How do paid promoters
change the review?
Rule 205 addresses compensation for promotion. On the intermediary’s
communication channel, an issuer may compensate a person to promote the
offering only with the required compensation disclosure. The issuer must
take reasonable steps to ensure that the promoter clearly discloses the
compensation with each communication.
Outside the intermediary’s communication channel, SEC staff says a
compensated third party’s communication must comply with Rule 204(b)’s
notice requirements. Therefore, hiring an agency, creator, publisher, or
other promoter does not expand the notice’s permitted content.
The issuer should also examine indirect involvement. SEC staff notes
that a media article may become a Rule 204 notice when it advertises
offering terms and the issuer helped prepare it. Accordingly, public
relations, guest articles, scripts, interviews, webinars, and sponsored
content need a documented channel and content review.
Finally, disclose the relationship accurately. A follower count,
audience description, prior campaign, or marketing projection does not
establish investor interest or predict an offering result.
Build a Reg CF
advertising review workflow
A useful workflow starts before anyone writes final copy. First, list
each planned channel, format, speaker, owner, publication date, and
audience. Then, connect every factual statement to the current source
record.
Next, separate reusable factual business information from
offering-specific messages. Also flag every reference to the security,
price, amount, closing date, use of proceeds, or funding progress. That
classification helps the reviewer apply the right rule and template.
Finally, assign approval and retention steps. Keep the approved
version, source materials, reviewer, date, platform link, disclosure,
and published copy together. If a filed fact changes, pause affected
communications until the team evaluates the update.
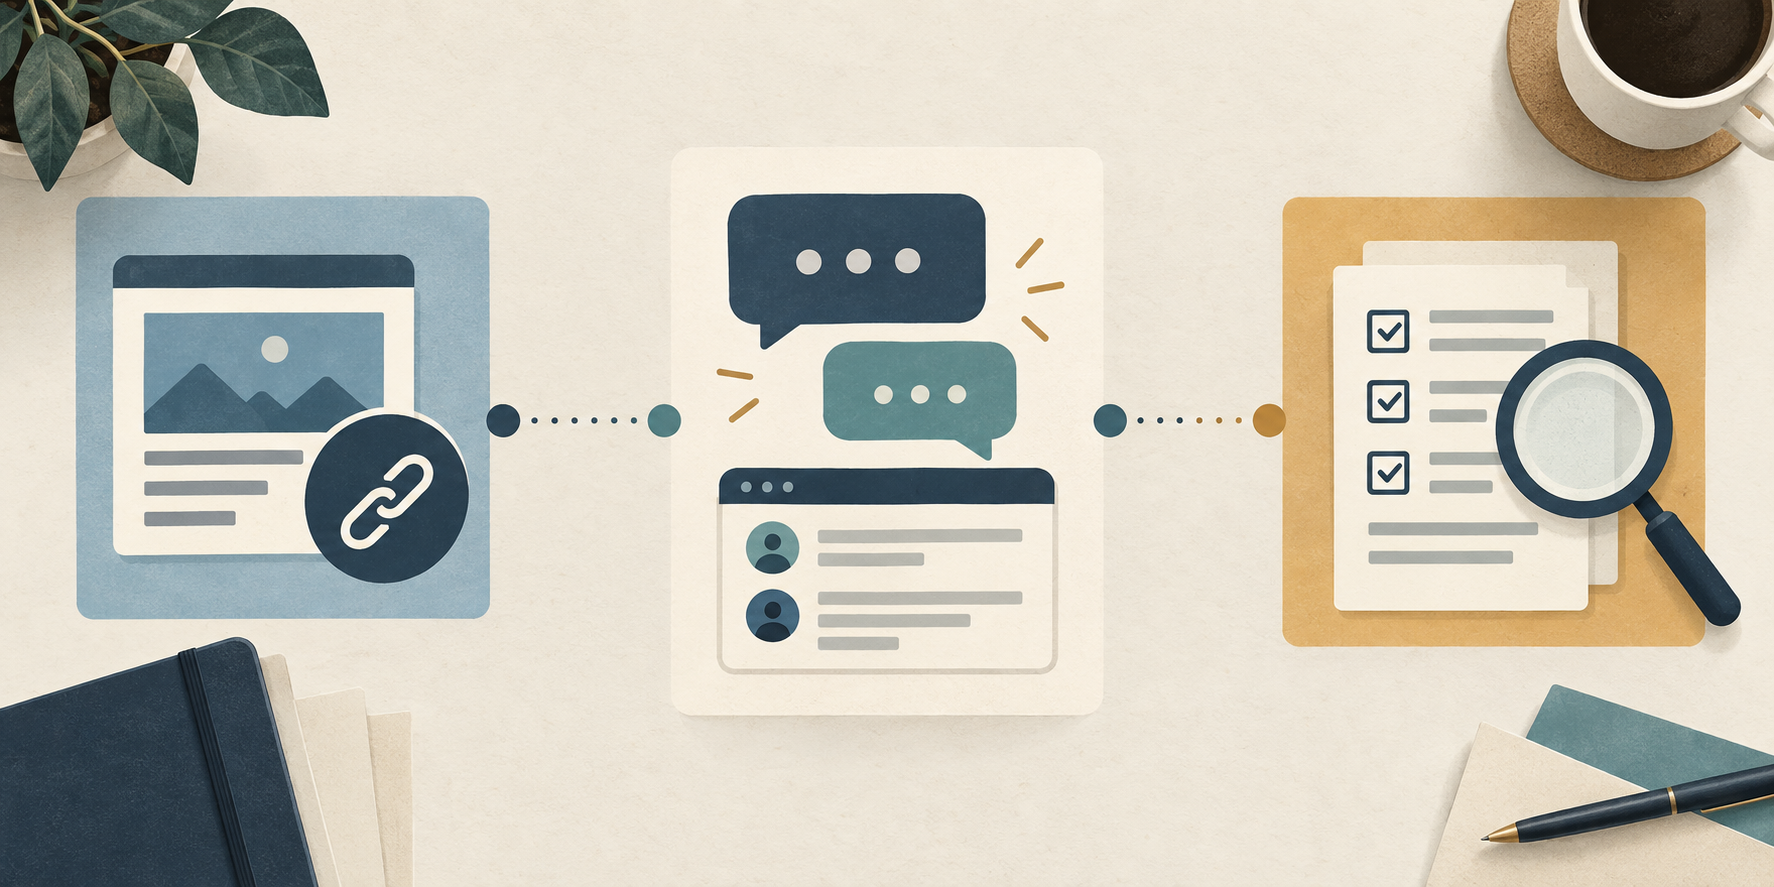
A review path should identify the channel, offering terms,
speaker, required disclosures, source record, and approver.
1. Mark the offering stage
First, record whether Form C has been filed. If the message comes
before filing, distinguish ordinary factual business information from a
Rule 206 solicitation of interest. Then, confirm the required legends
and filing treatment with counsel and the intended intermediary.
2. Mark the channel
Next, label the message as off-platform or inside the intermediary’s
communication channel. Include email, social media, websites, paid ads,
videos, podcasts, webinars, press outreach, and third-party posts. Do
not assume a format changes the rule.
3. Flag every offering term
Then, review the complete message for offering terms. Include
visuals, captions, headlines, link previews, spoken scripts, and
comments. A term can appear outside the main paragraph.
4. Draft from a controlled
source
Use the current Form C, approved platform page, and approved business
records. In addition, label management opinions and forward-looking
statements for specific legal review. Never convert a target or plan
into a statement of likely performance.
5. Check the speaker and
compensation
Identify everyone who prepared, approved, published, or paid for the
message. If a promoter receives compensation, document the arrangement
and required disclosure. Also confirm that each channel uses the
approved version.
6. Apply a conservative
content review
Remove false, exaggerated, unwarranted, promissory, or misleading
statements. Add material qualifications when their omission could
mislead. Moreover, do not imply SEC, FINRA, intermediary, or other
regulatory approval or endorsement.
7. Check privacy and
platform controls
Review consent, suppression, audience, tracking, and platform
requirements before using email lists, pixels, custom audiences, or
retargeting. The Invown issuer
marketing pixel addendum describes current issuer responsibilities
for supported integrations. However, it does not replace the issuer’s
own legal, privacy, or platform review.
8. Keep the record current
Finally, retain the approved content and evidence of what actually
appeared. Recheck scheduled posts, automated email, reusable creative,
and third-party placements after a material amendment or other relevant
change. A previously approved message can become inaccurate when the
underlying facts change.
A channel-by-channel
decision checklist
A Reg CF advertising rules checklist should connect the message to
its timing, channel, speaker, and source. Use these questions before
releasing a communication:
- Has the issuer filed Form C, or is the team relying on a pre-filing
communications rule? - Will the message appear away from the intermediary’s platform or in
its communication channel? - Does any part of the message include a term of the offering?
- If it is a Rule 204 notice, does it contain only permitted
information and a path to the intermediary? - Does every factual statement match a current source and the filed
disclosures? - Does the message identify the issuer or a representative’s
affiliation when required? - Is anyone compensated for promotion, and does each communication
carry the required disclosure? - Could a headline, visual, caption, omission, or link preview change
the message’s meaning? - Does the message avoid forecasts, outcome promises, regulatory
endorsement, and unsupported comparisons? - Have counsel, the intermediary, and other required reviewers
approved the final format? - Will the team retain the approved version, publication record, and
supporting evidence? - Is there a process to pause or revise future messages when facts
change?
This checklist organizes a review; it does not decide whether a
particular statement is lawful. Therefore, issuers should use the
current rules and qualified advisers for their facts.
Common mistakes to prevent
Several shortcuts can undermine an otherwise careful campaign:
- treating every social post as ordinary brand content;
- placing offering terms in a caption, image, hashtag, or link preview
outside the reviewed notice; - adding a forecast, testimonial, or urgency statement to a Rule 204
notice; - letting a paid promoter use different copy or omit compensation
disclosure; - answering platform questions from memory instead of the current
filing; - implying that portal access, SEC filing, or FINRA membership means
approval or endorsement; - describing a target, pipeline, valuation, demand signal, or business
plan as a likely result; - reusing approved content after a material fact changes; or
- failing to retain the final published version and its review
record.
Instead, make the approval path easy to follow. A short, sourced
message with a clear link is more useful than a crowded message that
mixes a notice, pitch, and prediction.
A practical next step
Reg CF advertising rules belong in the campaign plan before email,
social, paid media, public relations, or webinars begin. The issuer,
intermediary, counsel, and marketing team should agree on channels,
templates, disclosures, approval, and recordkeeping.
Invown Marketing Agency LLC provides optional marketing services
separately from Invown Funding Portal LLC. You can see Invown’s current
marketing packages to review the listed service options. Marketing
services do not establish issuer eligibility, ad approval, investor
demand, fundraising results, cost, or timing.
Invown Corp owns and maintains the site as a technology company. Reg
CF funding-portal activity identified on the site is conducted through
Invown Funding Portal LLC, an SEC-registered funding portal and FINRA
member. Invown does not provide legal, tax, financial, accounting, or
investment advice.
Sources and editorial review
notes
Primary and first-party sources reviewed September 25, 2026:
- 17
CFR 227.204, advertising, including the permitted contents of an
off-platform notice and the definition of offering terms. - 17
CFR 227.205, promoter compensation, including paid-promotion
disclosure and off-platform notice requirements. - SEC
Regulation Crowdfunding guidance for issuers, including Rules 204
and 205, intermediary-platform communications, and promoter
disclosure. - SEC
Regulation Crowdfunding interpretations, last updated July 9, 2026,
including current Rules 100, 204, and 205 interpretations. - FINRA
Funding Portal Rule 200(c), applied conservatively to the complete
public-facing package. - Invown
issuer marketing pixel addendum, marketing
packages, issuer
process, and offering-page
guide, checked for current service, entity, channel, and
issuer-context wording.
This article is educational information, not legal, tax, financial,
accounting, advertising, privacy, or investment advice. Issuers should
use the current rules, their own facts, their intermediary’s process,
and qualified advisers.