Crowdfunding audience readiness: An issuer checklist
Crowdfunding audience readiness means knowing whom your company can
lawfully and credibly reach before it plans a securities campaign. It is
not a required investor count or a prediction of demand. Instead, it is
a documented review of audience sources, communication permissions,
evidence quality, internal ownership, and the rules that may apply to
each message.
Key takeaways
- First, there is no universal audience size that makes a crowdfunding
offering ready or likely to reach its target. - Next, count only contacts the company can identify, reach, and
communicate with under applicable consent, privacy, platform, and
securities rules. - Also, separate ordinary business audiences from indications of
interest, investment commitments, and investors. - However, do not turn email opens, event attendance, customer
loyalty, or social reach into an investment-demand claim. - Finally, use the inventory to plan evidence and review steps, not to
promise a fundraising result.
What does
crowdfunding audience readiness measure?
A useful readiness review measures the quality of the issuer’s
audience records. Therefore, it starts with evidence rather than a
headline follower count.
For each audience source, ask four questions:
- Where did the contact come from?
- What permission or lawful basis supports the proposed
communication? - Who controls the source record and delivery channel?
- What conclusion does the evidence support without exaggeration?
For example, a current customer list may show that the company can
reach existing customers through an approved business channel. It does
not show that those customers qualify to invest, want to invest, or will
invest. Similarly, newsletter subscribers may have agreed to receive
certain emails. That consent may not cover every securities-related
message, advertising audience, or data use.
Consequently, audience readiness is narrower than popularity. It is
also more useful. A smaller, current, permission-based list with a clear
owner may support better planning than a large, stale list with unknown
sources.
Is there a
required number of potential investors?
No federal Reg CF rule sets a minimum audience or potential-investor
count before an issuer may prepare an offering. In addition, no audience
count can establish eligibility, intermediary acceptance, investor
interest, timing, or completion.
The issuer still needs a target amount, offering deadline, required
disclosures, financial statements, and an intermediary process. However,
those legal and operational items do not convert an audience estimate
into demand.
Moreover, Regulation Crowdfunding applies investment limits to
non-accredited investors across their Reg CF investments during a
12-month period. The intermediary must apply the applicable process
before accepting an investment commitment. Therefore, an issuer should
not divide a target amount by an assumed average commitment and present
the result as the number of investors it needs.
Instead, treat the audience inventory as one planning input. Counsel,
the intended intermediary, and qualified marketing and privacy reviewers
should assess the issuer’s actual facts and proposed channels.
Build a
crowdfunding audience readiness inventory
First, list every audience source separately. Do not combine
unrelated databases into one total.
Useful source groups may include:
- customers with current account or purchase records;
- newsletter subscribers with recorded opt-in information;
- event or webinar registrants with the applicable notice and consent
record; - members of a local, professional, alumni, or trade community;
- business partners and referral relationships;
- social followers or channel subscribers;
- website visitors covered by the issuer’s current privacy and consent
controls; and - people who lawfully submitted an indication of interest under a
reviewed testing-the-waters process.
Next, create one inventory row for each source. Record:
- source name and system of record;
- approximate record count and date checked;
- how and when the records were collected;
- permission, notice, or contractual basis for the proposed use;
- owner and authorized sender;
- available channels;
- recency and known quality issues;
- suppression, opt-out, or do-not-contact controls;
- geography or other relevant restrictions;
- approved message type; and
- reviewer and review date.
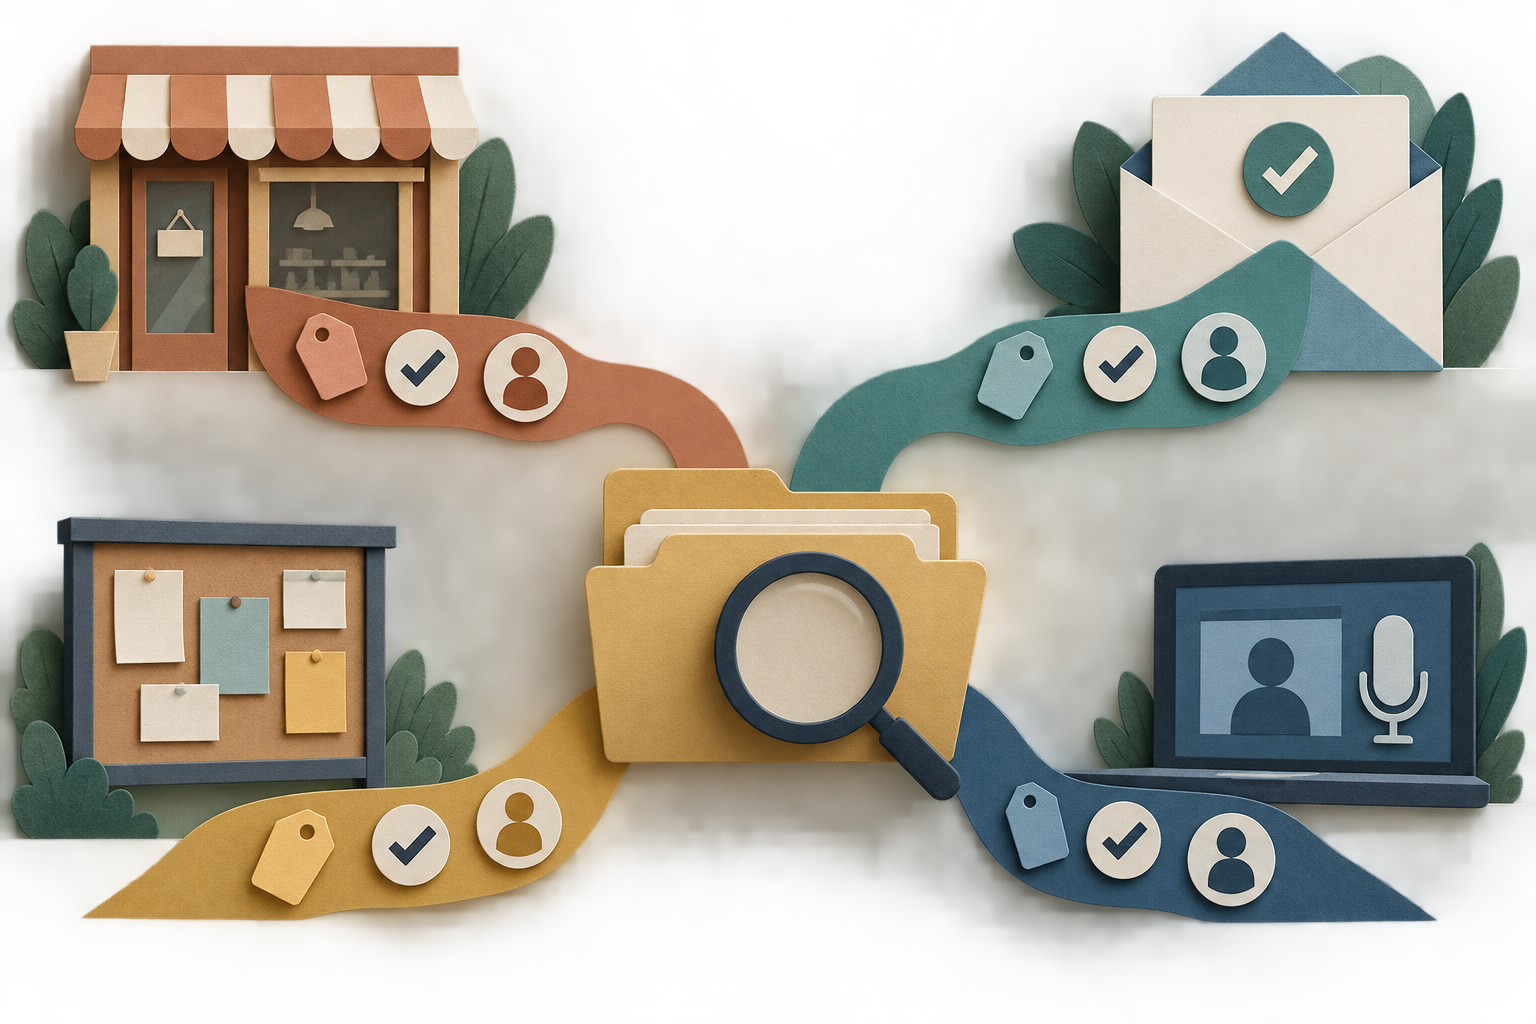
Review each audience source for permission, ownership, evidence,
and an appropriate communication path.
Then, keep the source rows separate from campaign results. An
inventory can record delivery, opt-out, and engagement data when the
issuer may lawfully use it. Yet the team should not describe those
signals as commitments, investor demand, or evidence that a target will
be reached.
Separate four kinds of
audience evidence
The word “audience” can hide important differences. Therefore,
classify records before using them in a plan.
1. Reachable business
contacts
These records show that a company has a current route to communicate
with a person or organization. Examples may include an opted-in
newsletter address or a customer account with current communication
preferences.
However, reachability does not establish interest in a securities
offering. It also does not establish investment eligibility or
capacity.
2. Engagement signals
Engagement may include attending an event, opening an email, visiting
a page, or responding to ordinary business content. These actions can
help a team review channel quality and message clarity.
Nevertheless, engagement is not an investment commitment. Avoid
labels such as “ready investor” unless the governing process and
evidence support that exact term.
3. Indications of interest
Before filing Form C, Rule 206 can permit an issuer to test the
waters for a contemplated Reg CF offering. However, the communication
must include required statements. It may not solicit or accept money or
any binding or nonbinding commitment before filing.
In addition, a written Rule 206 communication may include a way for a
person to indicate interest. That response creates no obligation or
commitment. Therefore, preserve the communication, required statements,
response method, and source record for counsel and intermediary
review.
4. Investment commitments
An investment commitment arises only through the applicable offering
process after filing and through the intermediary’s platform. It remains
subject to the offering terms, investor limits, cancellation rights,
material-change rules, and other requirements.
Consequently, do not place subscribers, followers, event attendees,
or indications of interest in the commitment category.
Review permissions
before choosing a channel
An audience source may be useful for one purpose and unavailable for
another. For that reason, review the proposed use before uploading,
matching, retargeting, emailing, texting, or sharing any records.
First, identify the company that collected the data. Next, locate the
privacy notice, consent record, contract, or other governing terms.
Also, check opt-outs, suppression lists, age restrictions, geography,
and vendor requirements.
Then, determine whether the proposed channel requires a new notice,
consent, agreement, or platform review. For example, an issuer may need
different controls for a direct email, an advertising audience, a
webinar, or a communication on the intermediary’s platform.
Invown’s issuer
marketing and pixel addendum describes current controls for issuer
marketing analytics and audience tools used with Invown listing pages.
It does not replace the issuer’s own privacy, advertising, platform, or
securities review.
Keep
pre-filing and live-offering messages separate
Timing changes the analysis. Therefore, maintain separate message
libraries and approval paths.
Before Form C is filed, ordinary factual business information may be
possible when it does not condition the market for an offering. In
addition, a properly structured Rule 206 communication may test interest
in a contemplated Reg CF offering. The facts and wording matter, so
counsel should review the actual plan.
After filing, Rule 204 limits off-platform communications that
advertise offering terms. A compliant notice must direct people to the
intermediary’s platform and include only the information allowed by the
rule. Meanwhile, an issuer may discuss offering terms through
communication channels on the intermediary’s platform when it identifies
itself as the issuer.
As a result, do not reuse an ordinary customer campaign, pre-filing
test, or social post as a live-offering message without a fresh
review.
Use an evidence-based
readiness checklist
An issuer may be ready for a deeper campaign-planning discussion when
it can answer “yes” to these questions:
- Can the team identify each audience source and its owner?
- Does each source have a current date, record count, and collection
method? - Are permission, notice, opt-out, and suppression records
available? - Can the team distinguish reach, engagement, indications of interest,
and commitments? - Have privacy, securities, platform, and communications reviewers
seen the intended channels? - Are pre-filing, testing-the-waters, and live-offering messages
separated? - Does every factual audience statement have a source and
qualification? - Can the company avoid presenting reach or engagement as likely
investment demand? - Are Invown Funding Portal LLC and Invown Marketing Agency LLC
assigned only their actual roles? - Is there an owner for corrections, withdrawals, opt-outs, and record
retention?
If an answer is “no,” document the gap. A visible limitation is more
useful than an invented audience total.
What audience readiness
cannot tell you
Crowdfunding audience readiness cannot show that an issuer qualifies
for Reg CF. It cannot show that an intermediary will accept the
offering. Also, it cannot predict how many people will invest, how much
they may invest, when an offering may close, or whether it will reach
its target.
The review also cannot replace financial-statement preparation, Form
C disclosure, background checks, offering-term analysis, escrow
arrangements, or intermediary review. In addition, marketing activity
cannot cure incomplete or misleading offering information.
Finally, avoid cross-issuer benchmarks unless the data, definitions,
cohort, period, limitations, and permission for use have been verified.
A percentage from another campaign may not apply to a different issuer,
audience, channel, security, or market.
A practical next step
Crowdfunding audience readiness begins with a source-controlled
inventory, not a promised number of investors. First, document where
each audience came from and what the issuer may communicate. Then,
separate reach and engagement from indications of interest and actual
commitments.
For help planning optional issuer communications, see Invown Marketing
Agency LLC’s current marketing packages. Package descriptions do not
establish eligibility, approval, audience availability, investor demand,
cost for a specific scope, timing, or fundraising results.
Invown Corp owns and maintains the general technology platform. Reg
CF funding-portal activity identified on the site is conducted through
Invown Funding Portal LLC, an SEC-registered funding portal and FINRA
member. Separately, Invown Marketing Agency LLC provides optional
marketing services. This article does not provide legal, tax,
accounting, financial, investment, privacy, or marketing-performance
advice.
Sources and editorial review
notes
Primary and first-party sources reviewed September 29, 2026:
- SEC
Regulation Crowdfunding guidance for issuers, including offering
limits, investor limits, intermediaries, disclosure, and
advertising. - Current
SEC Regulation Crowdfunding interpretations, last updated July 9,
2026. - 17
C.F.R. § 227.204, governing off-platform advertising of Reg CF
offering terms. - 17
C.F.R. § 227.206, governing Reg CF solicitations of interest before
Form C filing. - FINRA
Funding Portal Rule 200(c), applied conservatively to the complete
public package. - Invown’s issuer
process, marketing
packages, and issuer
marketing and pixel addendum, checked for current entity, service,
and communication wording.