Reg CF Rules: A Plain-English Guide
Reg CF rules let an eligible U.S. company raise money online from both accredited and non-accredited investors. Regulation Crowdfunding offerings must run through one SEC-registered intermediary. The company files Form C, investors review the disclosures, and the intermediary manages the regulated investment process.
This guide explains the main Reg CF rules in everyday language. It also shows what issuers, investors, and the intermediary each need to do. It is educational information, not legal, tax, accounting, financial, or investment advice.
Key takeaways
- An eligible issuer may sell up to an aggregate of $5 million under Reg CF during the applicable rolling 12-month period.
- The target amount is the minimum needed to complete the offering. The maximum is the most the issuer will accept.
- Non-accredited investors have annual Reg CF investment limits. Accredited investors do not have a Reg CF-specific investment cap.
- Form C, financial statements, campaign communications, and later reports all need separate attention.
- Investors can cancel until 48 hours before the offering deadline, subject to the rules governing changes and early closings.
Reg CF rules at a glance
| Stage | Issuer’s main job | Intermediary’s main job | What investors should do |
|---|---|---|---|
| Before filing | Confirm eligibility, choose terms, prepare Form C and financial statements | Review the issuer and offering under its regulatory duties | Learn how Reg CF works and decide how much loss they can bear |
| Before launch | File accurate disclosures and prepare compliant communications | Make required information public and complete required checks | Read the Form C, terms, financial information, and risks |
| During the raise | Keep information current and route material changes through the amendment process | Operate the platform, investment flow, communications channel, and required notices | Monitor changes and understand cancellation deadlines |
| At closing | Complete required filings and satisfy closing conditions | Direct the qualified third party to release or return funds when the rules allow | Confirm the final transaction and keep the records |
| After the raise | Complete annual reporting until a termination condition applies | Provide any contracted post-close technology or administration | Follow issuer updates and remember that resale may be difficult |
How much can a company raise under Reg CF?
An eligible company may sell up to $5 million of securities under Reg CF during a 12-month period. The calculation can include Reg CF sales by the issuer, certain entities under common control, and predecessors.
The SEC clarified in 2026 that each closing starts its own rolling 12-month measurement. That matters when an offering has more than one closing. A company should not assume that the full $5 million becomes available on the anniversary of the first closing.
For example, imagine an issuer closes on $500,000 in June and another $4.5 million in September. On the first closing’s anniversary, only that first $500,000 has rolled out of the 12-month calculation. The other $4.5 million remains part of the limit until its own anniversary.
Counsel and the intermediary should review the issuer’s actual history before the issuer selects a maximum. The $5 million ceiling is not an automatic promise that a proposed offering qualifies.
What are the target, maximum, and deadline?
Form C identifies three numbers that shape the offering:
- Target amount: the minimum amount the issuer must reach by the deadline for the offering to complete.
- Maximum amount: the most the issuer will accept if it accepts more than the target.
- Offering deadline: the date by which the target must be reached.
If commitments do not reach the target by the deadline, the offering does not complete. The intermediary then directs the return of committed funds. If the issuer will accept more than the target, Form C must explain the maximum, the oversubscription method, and the planned use of extra proceeds.
An issuer might set a $250,000 target and a $1 million maximum. Neither amount is guaranteed. The offering may complete after reaching the target, while accepting no more than the disclosed maximum under the stated allocation method.
The maximum can also affect the required level of financial statements. Therefore, an issuer should coordinate the target, maximum, use of proceeds, and accounting work before filing.
How much can an investor invest?
Accredited investors are not subject to a Reg CF-specific investment limit. Non-accredited investors have a limit across all of their Reg CF investments during a 12-month period.
Under the current rule:
- If either annual income or net worth is below $124,000, the limit is the greater of $2,500 or 5% of the greater of annual income or net worth.
- If both annual income and net worth are at least $124,000, the limit is 10% of the greater amount, capped at $124,000.
The limit is not a recommendation. An investor may qualify to invest more than would be prudent for that person. Reg CF securities are speculative, may be illiquid, and can result in the loss of the entire investment.
The intermediary must have a reasonable basis for believing that an investor remains within the applicable limit before accepting each commitment. It may rely on the investor’s representations unless it has reason to question them. Investors should therefore provide complete, current information about their income, net worth, and other Reg CF investments.
What financial statements does an issuer need?
The required financial statements depend on the current offering and other Reg CF sales during the applicable prior 12 months. If the issuer will accept more than the target, it uses the maximum amount in this calculation.
| Aggregate Reg CF amount | General requirement |
|---|---|
| $124,000 or less | Financial statements and specified tax-return information certified by the principal executive officer, unless reviewed or audited statements are already available |
| More than $124,000, up to $618,000 | Financial statements reviewed by an independent public accountant, unless audited statements are already available |
| More than $618,000, up to $1,235,000 | A first-time Reg CF issuer may provide reviewed statements; an issuer that has previously sold securities under Reg CF generally needs audited statements |
| More than $1,235,000 | Audited financial statements |
The statements generally cover the two most recently completed fiscal years, or the period since inception if the company is newer. They must follow U.S. generally accepted accounting principles and include the required statements and notes.
An issuer should involve an independent accountant early. The company’s bookkeeper or CFO cannot replace a required independent review or audit. The applicable rule, current Form C instructions, accountant, counsel, and intermediary should control the final determination.
What must Form C tell investors?
The issuer files Form C with the SEC and provides it to investors and the intermediary. The amount being raised is only one part of the offering statement.
Required information includes, among other items:
- the issuer’s legal identity, status, address, and website;
- directors, officers, and certain 20% beneficial owners;
- the business, business plan, employee count, and material risks;
- the target, maximum, deadline, price, security, and oversubscription method;
- a reasonably detailed use of proceeds;
- ownership, capitalization, debt, related-party transactions, and prior exempt offerings;
- financial condition and the required financial statements;
- the intermediary and its compensation; and
- where and when the issuer will make annual reports available.
Investors should read the complete filing, not just the campaign summary. The filed disclosure is the best place to understand the security, dilution, minority-owner risks, conflicts, debt, financial condition, and limits on resale.
Issuers should treat Form C, the offering page, financial records, pitch materials, and public statements as one controlled information set. If a fact changes, the team should determine whether the filing and other materials need to change too.
Can an issuer test interest before filing Form C?
Rule 206 allows an issuer to ask potential investors whether they might be interested before it files Form C. People often call this testing the waters.
The communication must clearly state that:
- no money or other consideration is being solicited and none will be accepted;
- no offer to buy can be accepted, and no purchase price can be received, until Form C is filed and only through the intermediary’s platform; and
- an indication of interest creates no obligation or commitment.
The issuer must retain the written communications and broadcast scripts, then file them as part of Form C. Testing interest is not the same as accepting reservations or investments, and positive responses do not predict a successful raise.
Coordinate the final testing-the-waters language and filing treatment with counsel and the intended intermediary.
What can an issuer advertise after filing?
After filing, an off-platform message that advertises the offering’s terms must fit Rule 204. The notice must direct people to the intermediary’s platform and may include only specified information:
- a statement that the issuer is conducting a Reg CF offering, the intermediary’s name, and a link in written communications;
- the offering terms, such as the amount, security, price, closing date, planned use of proceeds, and progress toward the target; and
- limited factual information about the issuer’s identity, location, contact details, and business.
The platform communication channel is different. Issuers may discuss the offering there, but they must identify themselves. Anyone acting for the issuer must disclose that relationship. A compensated promoter must clearly disclose the compensation with each platform communication.
Do not assume that a social post, email, interview, webinar, or testimonial is acceptable because it links to the offering. Review the message, speaker, channel, timing, and contents. Invown’s Reg CF advertising checklist explains this workflow in more detail.
When can investors cancel an investment commitment?
An investor may generally cancel until 48 hours before the offering deadline. The intermediary must tell the investor when that cancellation right ends.
An issuer may close early after the required information has been publicly available on the platform for at least 21 days. The issuer must also provide notice of the new deadline at least five business days before it arrives. The investor’s 48-hour cancellation cutoff then follows the new deadline.
If the issuer makes a material change, addition, or update, it files Form C/A. When the amendment requires reconfirmation, investors have five business days to act. Otherwise, the intermediary cancels their commitments and directs the return of funds.
Investors should watch the platform and email notices. Issuers should not describe commitments as final while a cancellation or reconfirmation right remains open.
Where is investor money held?
A funding portal does not hold investor money itself. It directs investors to send funds to a qualified third party, such as an eligible bank, credit union, or carrying broker-dealer.
The applicable escrow or funds provider can vary by offering. Investors should check the offering materials and transaction instructions instead of assuming that every Invown offering uses the same institution.
When the closing conditions are met and the cancellation period has passed, the funding portal directs the qualified third party to transmit funds to the issuer. If an investor cancels a commitment or the offering does not complete, the portal directs the return of the applicable funds.
What happens after the offering opens?
The filing work does not end when the campaign page goes live.
Changes during the offering
The issuer must file Form C/A for material changes, additions, or updates to information provided through the platform while the offering remains open. A material change can also trigger investor reconfirmation.
Progress updates
Form C-U generally reports progress after the issuer reaches 50% and 100% of its target. If the intermediary provides frequent public progress updates, those milestone filings may not apply. However, the issuer still files a final Form C-U reporting total securities sold no later than five business days after the offering deadline.
Annual reports
After selling securities under Reg CF, the issuer generally files Form C-AR within 120 days after the end of each covered fiscal year. The issuer also posts the annual report on its website. The issuer continues reporting until a Rule 202 termination condition applies and files Form C-TR when required.
If an offering remains open more than 120 days after fiscal year-end and a closing has already occurred, current SEC staff guidance may require both a Form C/A with updated financial statements and a Form C-AR. Coordinate the actual timeline with counsel and the intermediary.
For the full post-close workflow, use Invown’s Reg CF annual reporting checklist.
What does Invown handle, and what stays with the issuer?
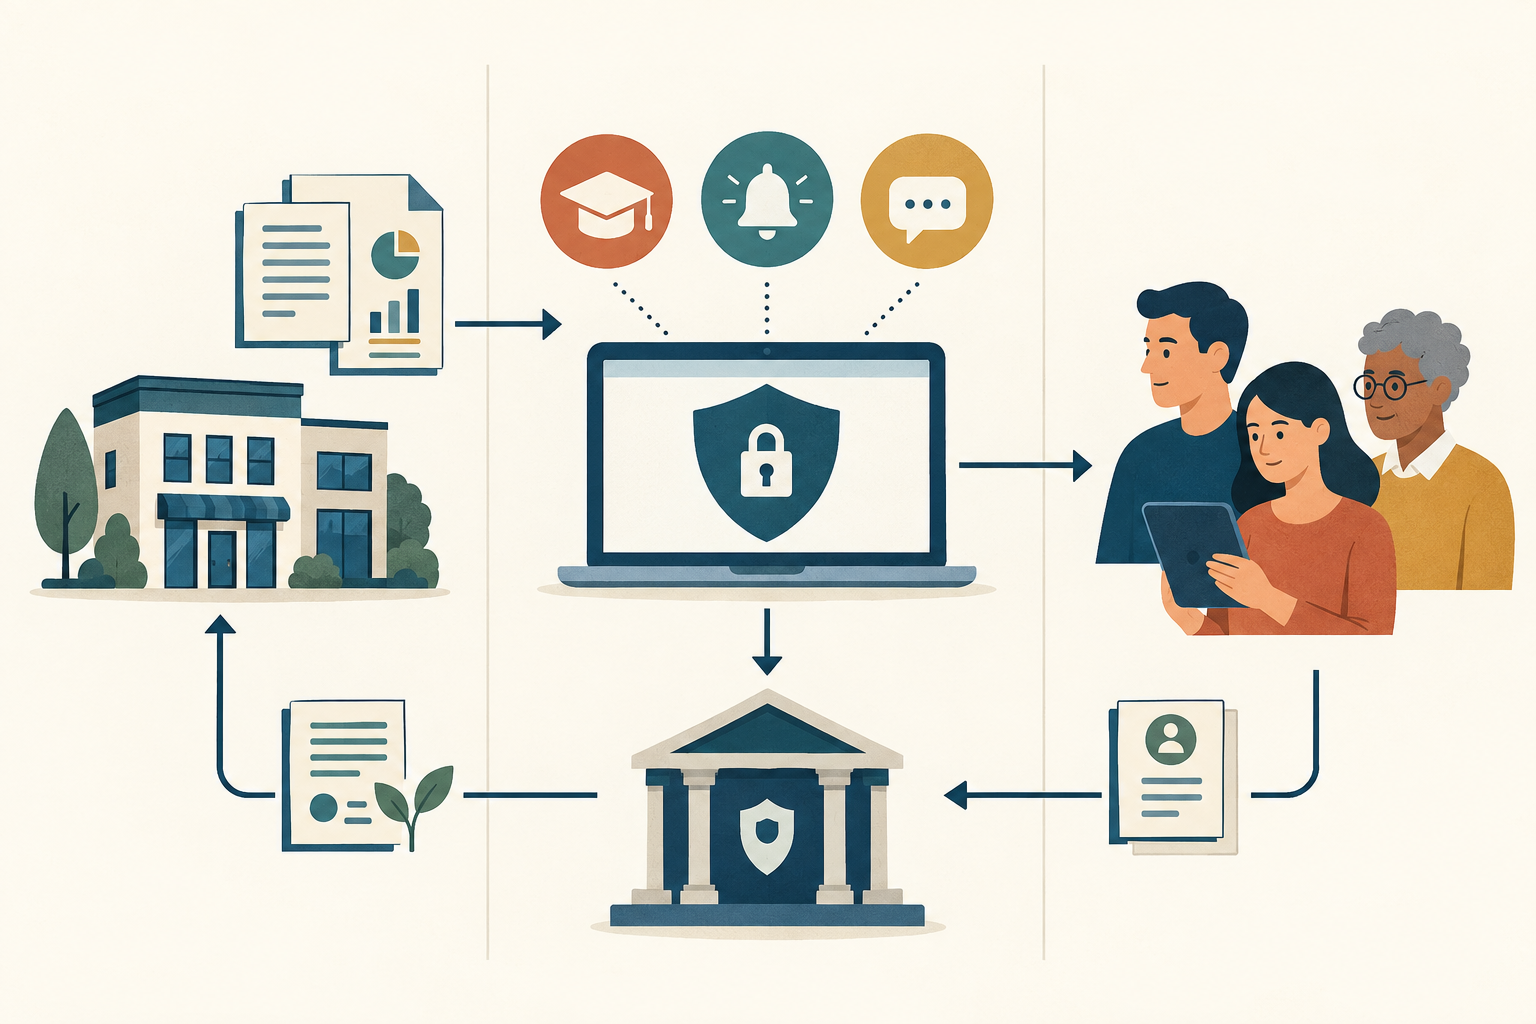
Reg CF divides responsibility. The registered intermediary has its own duties, while the issuer remains responsible for its disclosures, records, advisers, and communications.
| Area | Invown funding-portal process | Issuer responsibility |
|---|---|---|
| Offering access | Provides the online intermediary process for an accepted offering | Establishes eligibility and supplies accurate, complete information |
| Offering limits | Configures the disclosed offering maximum | Identifies prior Reg CF sales, related entities, and predecessors for review |
| Investor limits | Collects investor representations and applies the intermediary’s limit checks | Must not knowingly allow an investor to exceed the limit |
| Funds | Directs investors to the applicable qualified third party and issues required directions | Satisfies the disclosed closing conditions |
| Disclosures | Makes required issuer information available on the platform | Prepares, files, and keeps Form C and offering information accurate |
| Communications | Provides the public offering communication channel and required labels or controls | Identifies issuer representatives and compensated promoters; controls off-platform communications |
| Changes | Delivers platform notices and manages the applicable investor workflow | Determines and files required Form C/A amendments with advisers |
| Reporting | May provide contracted technology or administrative support | Remains responsible for required Form C-U, Form C-AR, and Form C-TR filings |
Invown Corp owns and maintains Invown.com as a technology company. Reg CF funding-portal activity identified on the site is conducted through Invown Funding Portal LLC, an SEC-registered funding portal and FINRA member. Invown does not provide legal, tax, accounting, financial, or investment advice.
A simple checklist for issuers
- Identify the exact legal issuer and any related entities or predecessors.
- Confirm eligibility and the available rolling 12-month offering amount.
- Choose a supportable target, maximum, deadline, and use of proceeds.
- Ask an independent accountant which financial-statement level applies.
- Build a source file for every material Form C statement.
- Align Form C, the campaign page, and all approved communications.
- Separate pre-filing testing-the-waters communications from post-filing advertising.
- Identify every founder, employee, representative, and paid promoter who may discuss the offering.
- Create a change-control process for Form C/A and investor reconfirmation.
- Calendar Form C-U, Form C-AR, website posting, and any Form C-TR work.
For a broader preparation sequence, see the Reg CF launch checklist.
A simple checklist for investors
- Confirm that the offering is conducted through the named registered intermediary.
- Read Form C, the financial statements, the security terms, and the material risks.
- Check how the target, maximum, oversubscriptions, and use of proceeds work.
- Give accurate information for the investment-limit calculation.
- Invest only an amount you can afford to lose entirely.
- Note the cancellation deadline and monitor amendment or reconfirmation notices.
- Expect limited liquidity and review the restrictions on resale.
- Keep the transaction confirmation and later issuer reports.
Invown’s investor education center provides more detail on the platform process and investment risks.
Ready to explore a Reg CF raise?
A Reg CF offering is a coordinated legal, accounting, disclosure, platform, and communication project. Identify the people, records, financial statements, and review steps before announcing a launch date.
See how raising works with Invown to understand the issuer process. Eligibility, structure, timing, acceptance, investor participation, and fundraising results depend on the facts and required review.
Frequently asked questions
Can any company use Reg CF?
No. The rule excludes several categories, including non-U.S. issuers, Exchange Act reporting companies, certain investment companies, blank-check companies, disqualified issuers, and some issuers that are delinquent in required Reg CF annual reports. Counsel and the intermediary should evaluate the actual issuer.
Does the SEC approve a Reg CF offering?
No. Filing Form C does not mean the SEC has approved the issuer, the securities, or the offering. Investors still need to evaluate the merits and risks.
Can an issuer use more than one funding portal for the same Reg CF offering?
No. A Reg CF offering must run exclusively through one intermediary’s platform.
Are Reg CF securities easy to resell?
Usually not. The securities generally face transfer restrictions during the first year, and a liquid market may never develop. Investors should expect to hold them for an indefinite period.
Does reaching the target guarantee a closing?
No. The target is one condition. The offering must also satisfy the applicable cancellation period, disclosures, intermediary process, and other stated closing conditions.
Sources and editorial review notes
Primary and first-party sources reviewed through September 29, 2026:
- SEC Regulation Crowdfunding: Guidance for Issuers
- SEC Regulation Crowdfunding Interpretations, last updated July 9, 2026
- 17 CFR 227.100: Crowdfunding exemption and requirements
- 17 CFR 227.201: Disclosure requirements
- 17 CFR 227.203: Filing requirements and form
- 17 CFR 227.204: Advertising
- 17 CFR 227.205: Promoter compensation
- 17 CFR 227.206: Solicitations of interest
- 17 CFR 227.303: Intermediary transaction requirements
- Invown issuer process, plus Invown’s current launch, advertising, annual-reporting, and investor-education resources